What to know before you buy
Before buying a property with an SMSF, a professional will have to review the setup of the trust to ensure that all laws and regulations are followed. Care must be taken to be sure the SMSF is structured to properly invest in a property.
What is the process for SMSF conveyancing?
The trustee for the SMSF will have to take steps to be sure that the SMSF has the legal right to buy or invest in a property. They will have to follow certain guidelines like being sure that the property is not being bought or sold by a member of the SMSF or a related party and that the sole purpose of the property is to provide retirement benefits.
Since 10 August 2026, an SMSF can't take out a new loan (a limited recourse borrowing arrangement, or LRBA) to buy residential property. New SMSF loans can only be used for business real property. Loans already in place, refinancing of those loans and contracts exchanged before that date aren't affected. For a new residential purchase, the fund pays the deposit and the balance from its own money.
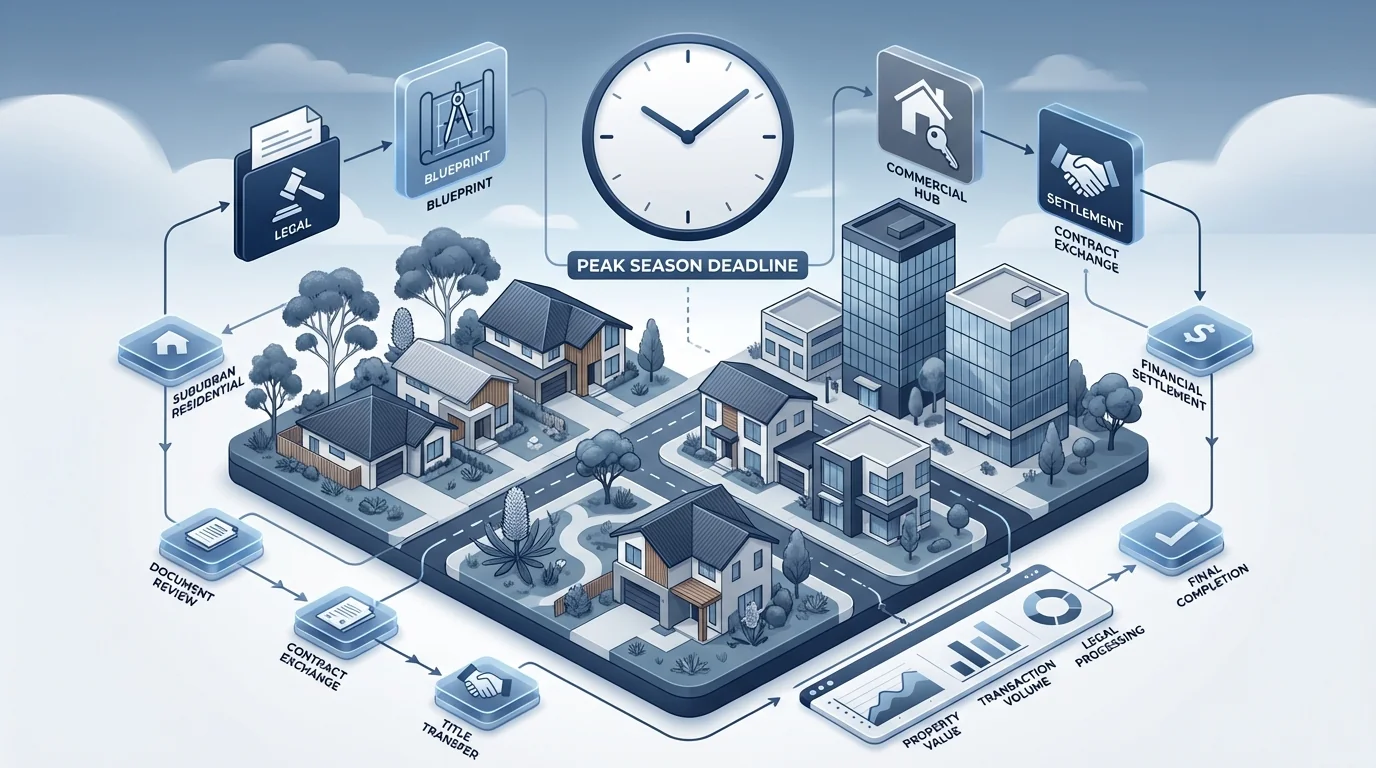
The property purchasing process will include:
Contract review
The seller will have the contract of sale prepared so that they can offer the property for sale. This document will usuallt be prepared by a legal professional and includes documents, certificates, and disclosures that pertain to the property.
After inspecting the property, the buyer can ask to review the contract with their legal representative. A lawyer should go through the contract to identify all important aspects of the sale, including the rate and terms.
Making an offer
The buyer will make an offer to the real estate agent of the seller. This happens the same way as with a normal offer. Special care must be taken to enter the correct details of the SMSF as the purchaser.
Because the fund can't borrow for a residential purchase, check that it has the full price plus stamp duty and costs before the trustee signs.
Paying the deposit
Once the offer is accepted, the buyer will usually pay a 10% deposit straight away. The seller's real estate agent, solicitor, or conveyancer will hold this deposit until the sale is finalised.
Cooling off period
After all contracts are signed, there will be a cooling-off period. The length and terms of the cooling off period vary from state to state.
Settlement
The buyer will pay the balance of the purchase price to the seller and the title to the property will be transferred. The trustee of the SMSF will then become the owner of the property.
Why do you need an SMSF Conveyancing Solicitor?
The laws surrounding SMSF conveyancing can be very strict and carry hefty consequences for those that don’t follow the rules. There are restrictions on borrowing, buying property from relatives and altering property, as well as a comprehensive set of compliance documentation that has to be maintained.
The ATO keeps a close eye on how SMSFs are set up and administered. They closely scrutinise all aspects of the conveyancing transaction, property transfer, leasing, banking, trusts, and stamp duty. It is critical to have an experienced SMSF conveyancer on your side that knows how to navigate this complicated landscape.
What are the usual Conveyancing Costs?
Buyers and sellers need to be sure that they pay all the fees needed to cover the legal side of a property purchase. These costs can generally be split into two categories: legal fees and disbursements.
The legal fees are what the conveyancer or solicitor charges for doing the work. Legal fees will be between $500 and $1500 depending on the circumstances of the transaction.
Disbursements are the costs associated with third parties that charge for services like special searches. There could be disbursements costs for things like:
- Title searches
- Rates and owners corporation certificates
- PEXA
- Transfer fees
- Bank fees
Disbursements are usually between $200 and $500 depending on whether the property has an owners corporation.