SMSF Property Conveyancing in Australia Is About to Get More Complex
If you're an SMSF trustee planning to purchase property in 2025 or 2026, there's a regulatory shift scheduled for the near future that is expected to affect your conveyancing experience. From 1 July 2026, Australia's anti-money laundering and counter-terrorism financing (AML/CTF) regime is expected to expand to cover lawyers, conveyancers, accountants, and real estate agents for the first time. These are the "Tranche 2" reforms, which are intended to add new procedural layers to every SMSF property transaction.
SMSF property purchases are already among the most documentation-heavy transactions in Australian conveyancing. Bare trust deeds, LRBA compliance, ATO reporting obligations, and lender requirements already create a process that typically runs 30 days longer than a standard residential purchase. Adding AUSTRAC-regulated identity checks and source-of-funds inquiries on top of that existing burden is likely to challenge the readiness of many trustees and their advisers.
Having handled over 2,500 SMSF property transactions across Australia, our team has seen how even small regulatory changes can lead to settlement delays. The 2026 reforms appear significant. Preparation for these changes involves understanding several key shifts.
The Implications of Tranche 2 AML Reforms for Conveyancers
Australia's AML/CTF laws have been in force since 2006, but they've mainly applied to banks, financial institutions, casinos, and remittance providers. The Tranche 2 reforms extend AUSTRAC's regulatory reach to what are called "designated non-financial businesses and professions" (DNFBPs). That includes the lawyers and conveyancers who handle your SMSF property settlement.
Under the new regime, conveyancers and lawyers providing property-related services may be required to:
- Register with AUSTRAC as reporting entities
- Conduct customer due diligence (CDD) before providing designated services
- Verify the identity of all parties to a transaction, including beneficial owners of trusts and corporate structures
- Assess and document the source of funds being used in the transaction
- Report suspicious matters to AUSTRAC
- Maintain detailed records for a minimum of seven years
For a standard residential purchase by an individual buyer, these steps add modest overhead. For an SMSF purchase, where the buying entity is a bare trust acting on behalf of a superannuation fund with a corporate trustee, the compliance chain may become considerably longer.
Why SMSF Transactions Are Expected to Feel the Impact
Think about the typical structure of an SMSF property acquisition using a limited recourse borrowing arrangement (LRBA). You have the SMSF itself, usually with a corporate trustee. You have the bare trust (or holding trust) that takes legal title to the property during the loan period. You may have individual trustees or directors behind the corporate trustee. And you have the SMSF members themselves.
Under the new AML/CTF requirements, your conveyancer may be required to identify and verify each layer of that structure. That means collecting identity documents for individual trustees or directors, verifying the corporate trustee's registration details, confirming the SMSF's ABN and trust deed particulars, and establishing who the beneficial owners are at every level.
Source-of-funds inquiries are expected to be another area of potential delay. SMSF property purchases typically involve a combination of accumulated superannuation balances, member contributions, and LRBA finance. Your conveyancer may need documented evidence showing where the deposit funds originated, how the loan was structured, and that the money flowing through the trust account has a legitimate and traceable origin. For trustees who are already providing similar documentation to their SMSF conveyancer and lender, some of this may feel familiar. But the formal AML/CTF requirements may demand a higher standard of verification than what's currently typical.
The SMSF Property Settlement Process: Where Delays May Emerge
Settlement timelines for SMSF purchases are already tight. Based on our experience across thousands of transactions, the average SMSF property settlement takes between 60 and 90 days from exchange to completion. That's roughly double the timeframe for a non-SMSF residential purchase in most Australian states.
The 2026 reforms are expected to add time at the front end of the process. Before your conveyancer can begin acting on your transaction, they'll need to complete their CDD obligations. If you're buying through a corporate trustee structure with multiple members, that verification process could take one to two weeks on its own, assuming all parties provide their documents promptly.
Where things get tricky is when documents are incomplete or inconsistent. A director whose name on their passport doesn't exactly match the ASIC records for the corporate trustee. A member who recently changed addresses and hasn't updated their identification. An overseas-resident member whose identity documents need additional verification steps. Each of these situations, which we encounter regularly in SMSF conveyancing, is expected to carry AML/CTF compliance implications on top of the existing regulatory requirements.
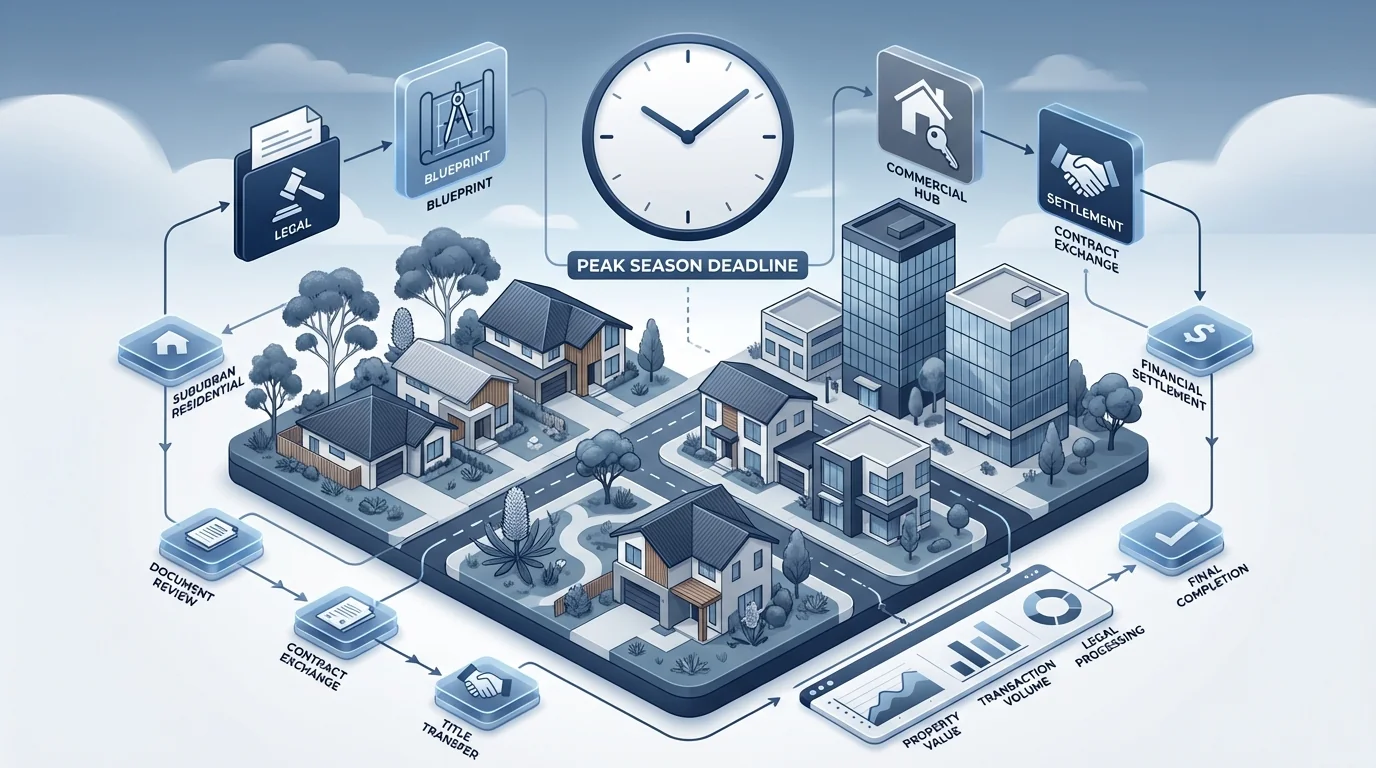
Trustees planning purchases during peak property season may wish to factor in extra lead time. The period between October and March already sees heavy transaction volumes, and adding new compliance steps during that window is likely to put pressure on every party in the settlement chain.
Source of Funds: The New Conversation Your Conveyancer May Have
Of all the new obligations, source-of-funds verification is an area that may catch SMSF trustees off guard. Banks already ask about this during the loan application process, but the AML/CTF requirements for conveyancers may operate independently and with their own standards.
For an SMSF property purchase, your conveyancer may need to see evidence that:
- The deposit funds came from the SMSF's bank account (not a personal account)
- Contributions used to build the deposit were made in compliance with contribution caps
- Loan funds were arranged through a compliant LRBA structure
- Any related-party transactions (such as a business real property purchase from a member) are properly documented
This is particularly relevant for commercial property purchases through an SMSF, where the property might be leased back to a member's business. The interrelationship between the parties can raise additional questions under an AML/CTF assessment, even when the arrangement is perfectly legitimate under superannuation law.
The ATO already requires SMSFs to maintain accurate asset valuations and reporting. The new AML/CTF obligations is expected to create a parallel set of documentation requirements that trustees need to manage alongside their existing compliance duties.
Practical Steps Trustees Can Take Now
The reforms are scheduled to commence on 1 July 2026, but preparation is often recommended to start well before that date. Trustees who get their documentation in order now may find themselves in a stronger position when the new rules take effect.
Trustees may wish to consider updating identification documents. Check that all trustees, directors, and members have current photo identification. If anyone's passport or driver's licence is due for renewal in the next 12 months, considering an early renewal may be helpful. Expired documents may not satisfy AML/CTF verification requirements.
It is often helpful to ensure ASIC records are current. If your SMSF has a corporate trustee, verifying that the company's registered details with ASIC are accurate and up to date is recommended. Director appointments, registered addresses, and shareholding details should all reflect the current position. Discrepancies between ASIC records and identity documents are one of the most common causes of verification delays we see in practice.
Maintaining organised financial records is recommended. Bank statements showing the accumulation of your SMSF's investment funds, contribution records, and rollover documentation may all become relevant to source-of-funds inquiries. Having these records accessible is intended to save time when your conveyancer requests them.
Consulting with an SMSF accountant and auditor may be beneficial. Your fund's annual compliance obligations are tracked through the ATO's SMSF reporting system. Making sure your fund is up to date with lodgements and audit requirements is expected to reduce the risk of complications when AML/CTF checks are layered on top of existing regulatory inquiries.
What We Don't Know Yet
The legislative framework is scheduled to be implemented, and the operational details are largely settled following the tabling of the AML/CTF Rules 2025. AUSTRAC is expected to provide ongoing guidance on how the new obligations apply to specific transaction types, including property conveyancing. The scope of "designated services" that trigger AML/CTF obligations for conveyancers was established following the finalisation of the AML/CTF Rules 2025, which were tabled in August 2025.
There are also open questions about how the new regime will interact with existing state and territory conveyancing regulations. Each Australian jurisdiction has its own requirements for electronic conveyancing, trust account management, and settlement procedures. How AUSTRAC's national AML/CTF obligations will mesh with these state-based systems is something the profession is still working through.
For SMSF trustees, this uncertainty means that the specific documents and information your conveyancer requests in mid-2026 may differ from what we'd predict today. The general direction is clear (more identification, more source-of-funds documentation, more verification of trust structures), but the precise requirements may shift as the implementation date approaches.
The Cost Question
New compliance obligations cost money to implement. Conveyancing firms will need to invest in AML/CTF compliance programs, staff training, technology systems, and ongoing monitoring processes. It is reasonable to suggest that some of these costs may be reflected in conveyancing fees from mid-2026 onwards.
For SMSF property transactions, where the compliance burden is already higher than standard purchases, the fee impact may be more pronounced. Trustees may wish to factor potential fee increases into their property acquisition budgets, particularly if they're planning purchases that are scheduled to settle after 1 July 2026.
The flip side is that stronger AML/CTF compliance across the property sector is intended to, over time, reduce the risk of fraud and money laundering in Australian property markets. As the government's guidance on SMSF property investment already notes, buying property through super involves particular risks and costs. The 2026 reforms add a new aspect to that risk profile, but they also add protections.
Getting Ready
The 2026 AML/CTF reforms are expected to represent the biggest change to Australian conveyancing regulation in decades. For SMSF trustees, who already deal with one of the most heavily regulated property purchase structures in the country, the additional compliance layers is likely to require careful planning and professional guidance.
If you're considering an SMSF property purchase that might settle around or after 1 July 2026, trustees may find it beneficial to speak with their conveyancer, accountant, and financial adviser about how these changes may affect your timeline and documentation requirements. The earlier you start those conversations, the less likely you are to face delays at settlement.
Our team is monitoring the implementation of these reforms closely and intend to update our processes as AUSTRAC releases further guidance. If you have questions about how the 2026 changes might affect your SMSF property transaction, you may call us or submit an enquiry through our website.